VA Loan Eligibility in Alabama and Florida: Where to Start
If you're considering a VA loan to buy a home in Alabama or Florida, you may be wondering whether you qualify and what to do first. Start by understanding how your service history, finances, and homebuying plans fit together.
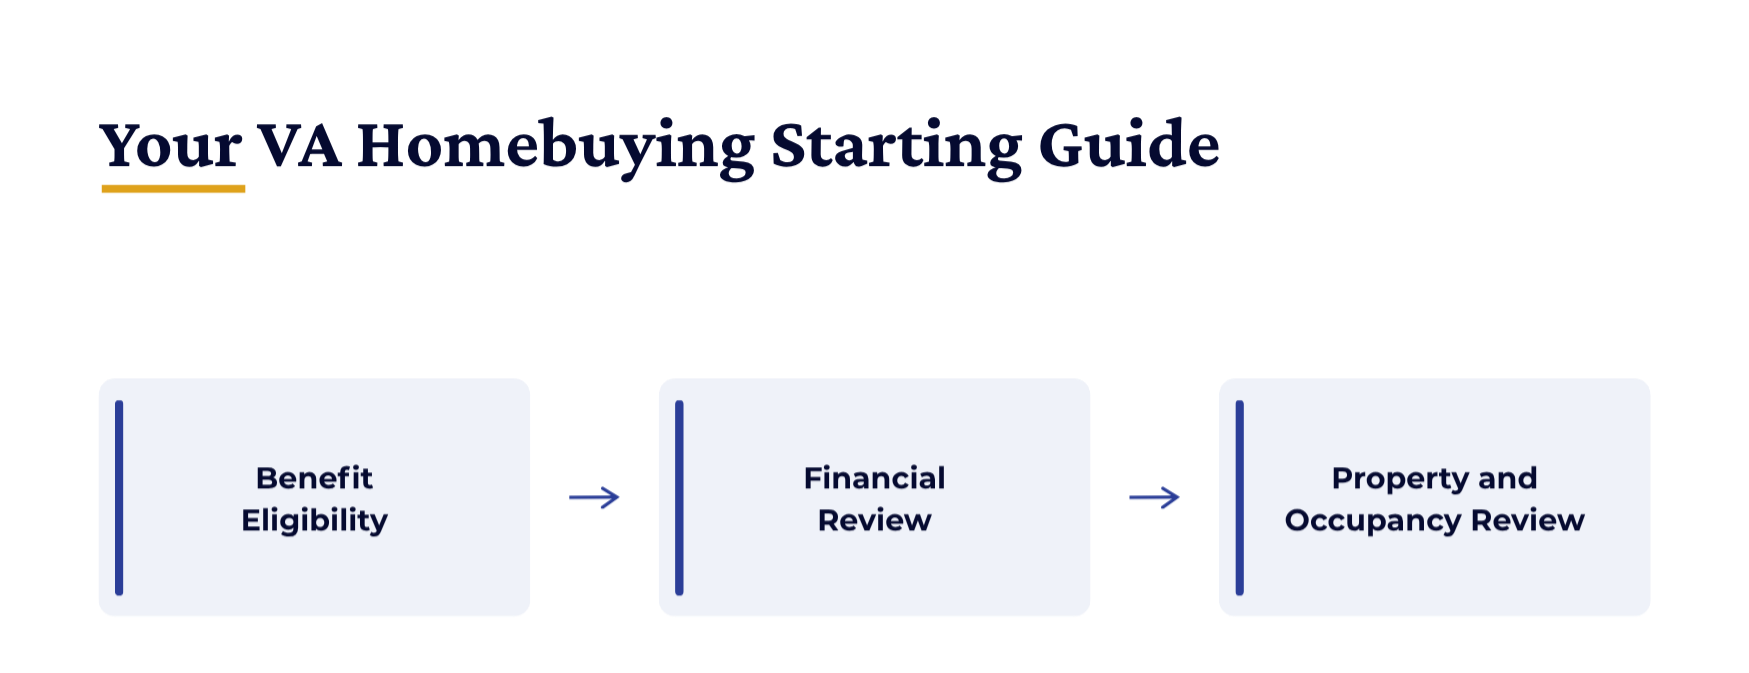
A VA-backed home purchase involves several separate checks. VA benefit eligibility establishes whether you can use the benefit. A lender then reviews your ability to repay the mortgage, and the home must satisfy the applicable property requirements. Understanding those steps can help you prepare for a useful first conversation.
At Homefront Lending, we help buyers across Alabama and Florida explore their financing options. Here is a practical place to begin.
Start with your VA benefit eligibility
Qualifying veterans, active-duty service members, National Guard members, Reservists, and certain surviving spouses may be eligible for VA home loan benefits. The requirements depend on your circumstances, including when and how you served and your discharge history.
A short service checklist cannot cover every situation. If your service record includes a qualifying exception or you are unsure which requirements apply, review the official VA guidance rather than assuming that you cannot use the benefit.
Review VA’s official home loan eligibility requirements
What your Certificate of Eligibility tells a lender
Your Certificate of Eligibility, often called a COE, helps verify your eligibility for the VA home loan benefit and shows information about your entitlement. It does not mean a lender has approved you for a mortgage or determined how much you can borrow.
You can request a COE through VA. A lender may also be able to help obtain it electronically. If you do not have yours yet, you can still ask questions about the process and which records to gather.
See VA’s instructions for requesting a COE
Understand what a lender will review
Benefit eligibility is one part of the process. The lender also needs to evaluate the mortgage you are requesting and your financial circumstances. That review can include your credit history, income, employment, debts, and assets.
Credit requirements can differ by lender
VA does not set a minimum credit score for a VA-backed home loan, but lenders may have their own requirements. A number you see in an article or advertisement may describe a particular lender’s policy. Ask which requirements apply to your situation and the financing options being considered.
Read VA’s explanation of entitlement and lender requirements
Your monthly obligations matter too
The review goes beyond a credit score. Lenders assess your income and monthly obligations, and VA underwriting also considers residual income: the amount available for family support after specified expenses. This helps assess whether the proposed mortgage fits alongside your other financial responsibilities.
Bring questions about student loans, car payments, childcare expenses, or income changes to your mortgage conversation. You do not need to calculate every underwriting measure yourself before asking where to start.
VA Lenders Handbook guidance on credit underwriting
Consider the home and your plans to live in it
For a VA-backed purchase loan, you generally need to plan to live in the home. If you have an upcoming permanent change of station, deployment, or another circumstance that affects your move, raise it early so we can review the applicable occupancy requirements.
The home also goes through a VA appraisal, which provides an opinion of value and considers minimum property requirements. An appraisal is different from a home inspection. A separate inspection can help you better understand the home’s condition before you move forward.
If you are considering a condominium, ask about VA project approval early. The property you choose can introduce additional questions alongside your own qualification review.
Learn about VA-backed purchase loans
Understand the VA homebuying and appraisal process
Plan for the full cost of owning the home
As you consider homes in Alabama or Florida, look beyond the mortgage principal and interest. Ask how property taxes, homeowners insurance, any required flood coverage, and association dues would affect your budget. Request property-specific estimates as your search narrows.
Standard homeowners insurance generally does not cover flood damage. Alabama and Florida insurance authorities explain this distinction, so ask an insurance professional what coverage a particular home may need.
Alabama homeowners insurance questions
Florida flood insurance guidance
Also discuss closing costs and whether a VA funding fee applies. Some borrowers qualify for a funding fee exemption. Your mortgage review should account for those costs and any applicable exemption rather than assume that every VA purchase has the same cash requirements.
Review VA funding fees and closing costs
Prepare for your first mortgage conversation
You don't need a complete application file to start asking questions. Having a few details available can make the conversation more useful:
Your service status and any service records you already have, such as a DD214 or statement of service.
Whether you have used a VA home loan before and whether you still own that property.
Your income sources and a general picture of monthly debt payments.
Where you hope to buy, your purchase timeline, and any relocation or PCS considerations.
A monthly housing budget that feels comfortable and questions about the cash you may need at closing.
The exact documents needed depend on your situation. Ask how to provide records securely before sharing service documents, account information, or other sensitive details.
A Practical First Step for VA Homebuyers
You do not need to have every detail figured out before exploring your VA home loan benefits. Whether you are purchasing your first home, relocating, or considering another property, understanding your eligibility and available entitlement is a useful place to begin.
A mortgage professional familiar with VA financing can help you review your circumstances, identify potential documentation needs, and understand the next steps in the financing process. The goal is to help you make informed decisions based on your situation rather than assumptions about what you may or may not qualify for.
Take the next step with clear questions
Your service history, financial circumstances, and plans for the home deserve a careful review. Start by asking what applies to you and what information would help clarify your options.
Explore Homefront Lending’s VA loan guidance
Speak with a Homefront Lending advisor about your next steps